
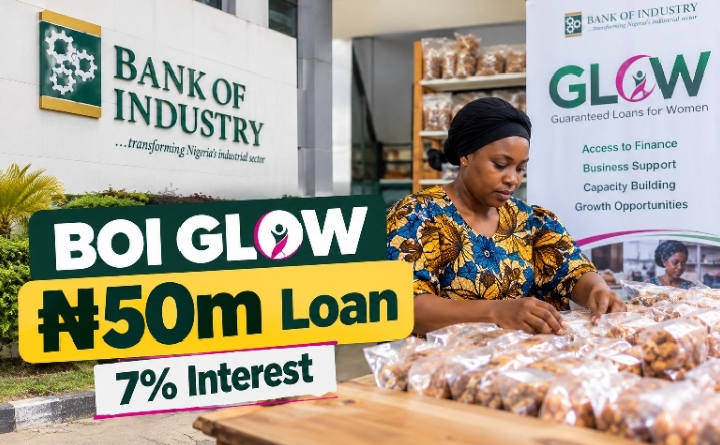
For many women building businesses in Nigeria, access to a large business loan can sound attractive until the figures, repayment terms and requirements begin to tell the fuller story. The Bank of Industry’s GLOW programme has entered that conversation with a financing ceiling of ₦50 million, a stated interest rate of 7% per annum and a structure specifically designed around women owned and women led businesses. The size of the facility immediately catches attention, but the real details sit behind that headline, from the type of business that can qualify to the documents required before financing can move forward.
GLOW is not simply an application where a business owner fills out a form and waits for ₦50 million to arrive. The programme has different financing limits for micro businesses and SMEs, specific requirements around CAC registration, BVN and NIN validation, business records, proposed use of funds and security. The 7% figure also needs to be understood properly because it represents the stated cost of the financing rather than free money. For anyone considering the programme, understanding how these pieces fit together can make the difference between seeing GLOW as a headline opportunity and understanding the actual facility being offered.
How the BOI GLOW programme works
GLOW means Guaranteed Loans for Women and is a Bank of Industry financing programme created around women owned and women led businesses in Nigeria. BOI presents the programme as more than a source of business finance, with business advisory services, mentorship, capacity building and strategic business development support forming part of the wider offering. The programme is therefore structured around helping eligible businesses obtain financing while also strengthening the businesses receiving the facility.
The headline figure attached to GLOW is ₦50 million, but that amount represents the maximum financing available to an individual beneficiary rather than a standard amount every applicant receives. BOI’s product documentation places micro businesses at a maximum of ₦10 million, while SMEs can access financing ranging from ₦10 million to ₦50 million, subject to the applicable assessment, business needs and facility requirements. The distinction is important because a business applying for GLOW should approach the application based on its actual financing needs and capacity rather than simply choosing the highest available figure.
The broader GLOW financing framework is valued at up to ₦10 billion. BOI and the National Credit Guarantee Company established the arrangement in January 2026 to support guaranteed financing for eligible women owned enterprises. The ₦10 billion figure therefore describes the wider programme financing framework, while ₦50 million represents the maximum facility that can be available to one beneficiary under the stated product limits.
What happened on January 26, 2026
A significant development for GLOW came on January 26, 2026, when BOI announced its partnership with the National Credit Guarantee Company, commonly referred to as NCGC, around the programme. The arrangement provided for up to ₦10 billion in guaranteed financing for women owned businesses through GLOW, with NCGC providing a 25% credit guarantee cover on eligible BOI loans.
The guarantee is important because it is designed to reduce part of the lending risk attached to eligible businesses. It does not mean that an applicant receives money without assessment, and it does not remove the repayment obligation attached to the loan. The presence of the guarantee should therefore be understood as part of the financing structure between the institutions rather than as a promise that every woman who registers will automatically receive funding.
BOI also disclosed around that January 2026 announcement that more than 33,000 loan applications were in progress, representing financing demand of more than ₦65 billion. That figure describes applications and estimated financing demand rather than money already disbursed to applicants. It is therefore important to keep the distinction clear when discussing the scale of interest surrounding the programme.
Later 2026 BOI impact material also described GLOW as a ₦10 billion gender focused fund offering financing of up to ₦50 million per beneficiary and referred to more than 41,000 prospective beneficiaries in 2025. Those figures provide additional context around the scale of the programme, although prospective beneficiaries should not be confused with confirmed loan recipients or actual disbursements.
Why the ₦50 million figure is a loan
The biggest point to understand before considering GLOW is that the ₦50 million is not a grant. The facility is repayable financing provided under the terms approved for the business, meaning an applicant who receives the money is expected to repay the principal together with the applicable financing cost.
BOI’s product documentation states an interest rate of 7% per annum, described as all inclusive for the GLOW financing. The stated rate is therefore not a cash award attached to registration. It is the financing cost attached to a loan that must be repaid according to the approved repayment structure.
This distinction becomes particularly important when a business owner sees the ₦50 million figure without reading the facility terms. A business receiving ₦50 million would have a financing obligation rather than ₦50 million of disposable business income. The amount borrowed, the interest charged, the repayment period and the approved purpose of the facility all form part of the financial commitment.
What does the 7% interest rate mean
The 7% per annum rate means the facility carries a stated annual interest cost of 7% under the GLOW product terms. BOI describes the pricing as all inclusive and its product documentation also states that there is no appraisal fee, commitment fee or monitoring fee under the listed product structure.
That does not mean every possible cost connected with financing disappears. BOI’s documentation indicates that insurance and legal costs may apply depending on the facility and security structure. An applicant should therefore look at the full financing documentation rather than calculating the cost solely from the headline interest figure.
For a simple illustration, 7% of ₦10 million is ₦700,000 for 1 year before considering the actual repayment structure, timing of repayments, principal reductions and any applicable costs. The actual repayment obligation should therefore be based on the repayment schedule approved by BOI rather than multiplying 7% by the original facility and assuming that calculation represents the complete amount payable.
How long can the financing last
GLOW provides different repayment periods depending on the type of facility being approved. A term loan can have a tenor of up to 5 years, while working capital financing can run for up to 3 years, inclusive of the applicable moratorium and subject to the project’s cash flow.
The distinction between the 2 financing purposes is useful because businesses do not always need money for the same reason. A company purchasing machinery may require a longer repayment period because the equipment is expected to generate income over time, while a business purchasing raw materials may require financing that follows a shorter operating cycle.
Cash flow therefore becomes an important part of the application. A business requesting financing should be able to demonstrate how the proposed facility connects with its operations and how the business is expected to generate the funds needed for repayment. The maximum tenor is not necessarily the period every applicant will receive because the final structure depends on the facility and assessment.
Who can apply for GLOW
GLOW is designed for women owned and women led businesses, with the programme focused on expanding access to finance and business support for women entrepreneurs. The intended beneficiaries are therefore businesses rather than individuals simply seeking personal cash.
The current registration process also makes the business connection clear because applicants are required to provide a CAC business registration number beginning with RC or BN. The portal asks for personal information including BVN, NIN, full name, date of birth, gender, phone number, home address and email, together with business registration information.
The CAC number is used to validate the business information and can be used to populate business details during the registration process. This means a woman operating an informal business without CAC registration should not assume that she can proceed directly to the GLOW financing facility using only her personal details.
Why CAC registration matters
CAC registration is one of the clearest requirements visible in the current GLOW registration process. The portal requests an RC or BN number, allowing BOI to verify the registered business and connect the application to the relevant business information.
For an enterprise registered under a business name, the documentation requirements differ from those of a limited liability company, but both structures require formal business records. The application therefore moves beyond simply proving that the applicant is a woman running a business and into establishing that there is a recognised business entity that can be assessed for financing.
Business owners considering GLOW should make sure their CAC records are accurate before starting the process. A mismatch between the information supplied during registration and the registered business information can create additional questions during verification and assessment.
Businesses covered by GLOW
GLOW covers businesses operating across a range of productive sectors rather than limiting financing to one particular type of enterprise. The January 2026 BOI and NCGC announcement specifically identified manufacturing and processing, ICT and digital services, e commerce, creative and entertainment industries, healthcare, education, renewable energy and waste management among the sectors covered.
The wider product description also presents GLOW as financing for women businesses across different sectors, meaning the programme is not structured around a single industry. The important issue is that the proposed financing should relate to an eligible business activity and an approved productive purpose.
A business owner should therefore be able to explain exactly how the requested money will be used. Whether the request concerns equipment, machinery, raw materials or another approved business need, the application should connect the amount requested to the actual operation and growth needs of the business.
How the money can be used
GLOW financing is structured around productive business purposes rather than personal consumption. The product documentation identifies term loan financing for productive assets and equipment, while working capital financing can support eligible inputs such as raw materials.
A manufacturing business, for example, could require equipment that increases production capacity, while a processing business may need machinery or production inputs. A digital business may have different eligible financing needs, depending on the nature of its operations and the facility approved by BOI.
The important point is that the business should have a clear reason for requesting the money. Applicants may need pro forma invoices or quotations for proposed purchases, while the business case and cash flow projections help establish how the financing fits into the wider operation.
How much can a micro business receive
Micro businesses can access up to ₦10 million under the stated GLOW product limits. That figure represents the maximum single obligor limit for the micro business category rather than a guaranteed amount available to every micro business that applies.
SMEs occupy the higher financing range, with the product documentation placing the facility between ₦10 million and ₦50 million. The distinction means the ₦50 million headline is principally relevant to the upper end of the SME financing structure rather than every business registered on the portal.
The amount approved will ultimately depend on the business, the purpose of the facility, its financial position, the supporting documents, the repayment capacity and the security requirements applicable to the request. Applying for the maximum amount therefore does not automatically translate into approval for the maximum amount.
What security may be required
The word guaranteed in GLOW can create confusion around collateral and security. The NCGC guarantee is part of the credit structure, but it does not mean every loan is automatically unsecured.
For micro facilities up to ₦10 million, BOI’s product documentation lists security arrangements that can include charges over existing and future equipment and stock, insurance over financed assets, credit life insurance for the chief promoter, a Global Standing Instruction linked to BVN accounts, a personal guarantee from the chief promoter and external guarantors depending on the size of the facility.
Facilities of ₦10 million and above can involve additional security arrangements. BOI’s documentation lists possibilities including an all asset debenture, acceptable landed property, a third party legal mortgage, a bank guarantee and personal guarantees from relevant company directors, depending on the applicable facility.
This means an applicant should not interpret GLOW as a ₦50 million facility that comes without security requirements. The actual security package depends on the business and the financing structure approved by BOI.
Guarantor requirements for smaller facilities
External guarantors can form part of the security requirements for smaller GLOW facilities. BOI’s product documentation identifies several categories of people who may qualify, subject to verification and acceptance.
The listed categories include eligible civil servants, bankers, professionals such as doctors, lawyers, accountants and engineers, confirmed employees of reputable companies, employees of international oil companies and telecommunications companies, as well as owners of CAC registered businesses.
The guarantor must be verifiable and acceptable to BOI, with the documentation also referring to a notarised statement of net worth. The requirements become more specific according to the size of the facility.
For facilities below ₦5 million, the product documentation provides for 1 external guarantor, while facilities from ₦5 million to ₦10 million require 2 external guarantors under the listed structure.
Documents an applicant should prepare
The application process goes considerably deeper than entering personal information on the GLOW portal. For an enterprise or business name structure, BOI’s listed documentation includes CAC registration documents, a formal application letter, a feasibility report or business case, pro forma invoices or quotations for equipment or raw materials, business or promoter bank statements and valid identification documents.
Applicants may also need a CV for the promoter and key management personnel, a utility bill, cash flow projections, evidence of lease where applicable, guarantor net worth documentation, guarantor identification and passport photographs. Relevant industry licences or certifications may also be required depending on the nature of the business.
The documentation can extend further where applicable, including existing asset valuation, payroll reports, BOI environmental and social assessment documentation and an HR policy. The exact package can differ according to the business structure, financing amount and nature of the proposed facility.
Requirements for limited liability companies
Limited liability companies face a corporate documentation process that reflects the structure of the business. BOI’s documentation includes the Certificate of Incorporation, CAC share allotment documentation, particulars of directors and MEMART, alongside the formal application letter and feasibility report or business case.
The company may also be required to provide pro forma invoices, company bank statements, identification documents and CVs of the promoter and key management personnel, together with a utility bill and other supporting information.
Additional records can include tax clearance, CAC annual returns, audited accounts, management accounts, cash flow projections and security documentation where applicable. Businesses seeking larger financing should therefore prepare their corporate and financial records before beginning the application process.
How the GLOW application starts
The current GLOW registration portal provides the entry point for applicants. Registration begins with personal and identity validation, including BVN and NIN, before the applicant supplies the CAC business registration number and other required details.
Once the business information is verified, the applicant proceeds through the registration and pre approval process. The business information, financing request and supporting documentation then form part of the assessment carried out under BOI’s financing process.
A typical application journey therefore moves from account creation and identity validation to business verification, application completion, document submission, assessment, security documentation where required and eventual disbursement if the facility is approved.
The exact sequence can vary according to the applicant and facility, so business owners should follow the instructions shown on the official GLOW portal during registration rather than relying entirely on a generic checklist.
What happens after registration
Creating a GLOW account is not the same thing as receiving approval. Registration gives the applicant access to the application process, while the actual financing decision depends on BOI’s assessment of the business and requested facility.
The assessment can involve reviewing the business model, financial information, cash flow, proposed use of funds, repayment capacity, supporting documents and applicable security. Businesses requesting larger amounts should expect a more substantial level of documentation because the financing exposure is higher.
Once a facility is approved, the applicant must complete the applicable documentation and security requirements before disbursement. The loan is then subject to the approved terms, including the interest rate, tenor, repayment arrangement and permitted use of funds.
Is there a GLOW deadline?
No official current closing date was identified in the BOI GLOW information available for the programme. The dedicated registration portal remains accessible, and BOI continues to present GLOW as an active financing product.
That makes it important to distinguish the official programme information from dates published by third party opportunity websites. A deadline should only be presented as official if BOI itself announces one.
For applicants, the safer position is that registration and applications are available through the official GLOW process, while no official current deadline should be assumed unless BOI publishes a new closing date.
Why the 25% NCGC guarantee matters
The 25% NCGC guarantee is one of the defining features of the current GLOW financing structure. Under the January 2026 arrangement, NCGC provides a 25% credit guarantee cover on eligible BOI loans under the programme.
That guarantee is designed to support lending by taking on part of the credit risk associated with eligible facilities. It can therefore play an important role in the financing framework, particularly where businesses face challenges accessing conventional credit.
The guarantee should still be viewed within the wider lending structure. The borrower remains responsible for the loan, and the existence of a guarantee does not remove the need for proper business assessment, documentation, security where applicable or repayment.
What makes GLOW different from a grant opportunity
The difference between GLOW and a grant programme comes down to the financial obligation attached to the money. A grant generally does not require the beneficiary to repay the principal under ordinary grant conditions, while GLOW provides repayable financing.
That distinction changes how a business owner should approach the application. Instead of simply asking how much money can be obtained, the applicant should consider how much the business can responsibly deploy and repay.
The 7% annual interest rate, a term loan tenor of up to 5 years and working capital tenor of up to 3 years create a financing structure that needs to fit the business’s cash flow. A larger facility can provide more capital, but it also creates a larger repayment responsibility.
The figures applicants should remember
The most important figures attached to GLOW are straightforward once the programme is separated into its different layers. The wider financing framework is up to ₦10 billion, while the maximum individual facility is ₦50 million.
Micro businesses can access up to ₦10 million, while SMEs can seek financing from ₦10 million to ₦50 million. The stated interest rate is 7% per annum, with term loan financing available for up to 5 years and working capital financing available for up to 3 years.
The NCGC guarantee covers 25% of eligible BOI loans under the arrangement. Those figures describe the structure of the programme, but they should not be interpreted as guarantees that every applicant will receive the maximum amount or qualify for the same repayment terms.
How women business owners should approach the application
A business owner considering GLOW should begin by looking at the business itself rather than the ₦50 million headline. The first question is how much financing the business actually needs, followed by what the money will purchase, how those purchases will generate business activity and how the resulting cash flow can support repayment.
CAC records, bank statements, financial projections, invoices, quotations, identification documents and other supporting records should be organised before the application moves deeply into assessment. Businesses with clearer records can present a more complete picture of their operations and financing needs.
The proposed amount should also make sense for the scale of the business. A company seeking ₦50 million should be prepared to explain why that amount is required and how it fits into the business plan, rather than treating the maximum facility as an automatic target.
Where applicants can begin
The current registration process is available through the official BOI GLOW portal, where applicants can create an account and begin the verification process. The portal requires BVN and NIN validation and asks for CAC business registration information before the application proceeds.
Applicants should use the official portal and rely on the instructions presented during registration because the documentation and assessment requirements can vary depending on the business structure and facility being requested.
The central point remains clear: GLOW provides women owned and women led businesses in Nigeria with access to BOI financing of up to ₦50 million, but the facility is repayable and subject to assessment. The 7% per annum rate, the available repayment periods, the CAC requirement, the security structure and the NCGC guarantee all form part of the programme that sits behind the headline figure.
For a woman running a registered business and looking for financing for equipment, working capital or other eligible productive purposes, understanding those terms is the starting point. The ₦50 million figure may be the number that attracts attention, but the eligibility requirements, business documents, financing purpose and repayment structure determine how the opportunity actually works for an applicant.