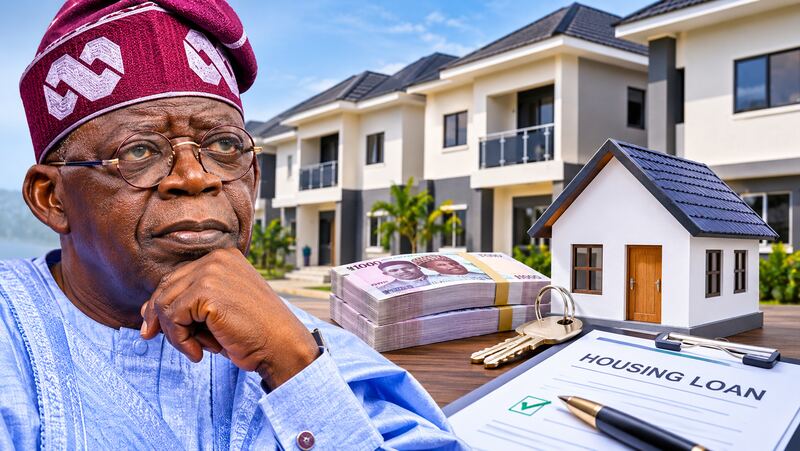
President Bola Tinubu has told Nigerians that eligible homebuyers can now borrow up to ₦100 million at a fixed interest rate of 9.75% and repay over 20 years, with a minimum deposit of 10% of the property price. The announcement was made on Tuesday, November 17, 2026, in a message on his verified X handle, @officialABAT.
For anyone who has spent years handing a landlord a fat cheque every January, the numbers are hard to ignore. Commercial bank lending in Nigeria still sits at around 27% or more, according to figures cited by Premium Times. A fixed 9.75% for two decades is a very different proposition.
But the headline needs some unpacking. This is a mortgage, not a grant. You still have to qualify, find a completed house with clean papers, and pay the money back. Here is what the Tinubu ₦100m housing loan actually offers, who can get it, what it costs month to month, and how to start an application.
What President Tinubu announced
The president said the facility comes from the ₦1 trillion MOFI Real Estate Investment Fund, known as MREIF, and forms part of the economic reforms his administration began in 2023. He said access would depend on eligibility and not on political connections or personal relationships.
He framed the scheme around a problem most tenants know well. “Imagine paying house rent for 25 years,” he said, pointing to Nigerians who spend most of their working lives renting and end up owning nothing.
Alongside the MREIF loan, Tinubu also highlighted a second, separate product from the Federal Mortgage Bank of Nigeria (FMBN): loans of up to ₦50 million at 6% interest, repayable over up to 30 years, for eligible contributors to the National Housing Fund. We compare the two further down.
Tinubu ₦100m housing loan at a glance
| Feature | Details |
|---|---|
| Funding source | MOFI Real Estate Investment Fund (MREIF), ₦1 trillion programme |
| Maximum loan | Up to ₦100 million (subject to affordability) |
| Interest rate | 9.75% per annum, fixed for the life of the loan |
| Repayment period | Up to 20 years |
| Minimum deposit | 10% of the property price |
| Property type | Completed residential homes with registered title |
| Who lends | Participating banks and financial institutions, including FirstBank, Stanbic IBTC and Sterling Bank |
| Joint applications | Allowed for couples |
| Pension option | Eligible contributors may use part of their RSA balance towards the deposit, subject to the rules |
What the monthly repayment looks like
The president gave one example. Buy a ₦10 million house, put down ₦1 million, borrow the remaining ₦9 million, and you repay about ₦85,400 a month over 20 years. We ran the standard repayment formula at 9.75% over 240 months to check, and the figure holds up.
The same maths applies to bigger loans. The table below shows estimated monthly repayments for different property prices, assuming the 10% minimum deposit and the full 20-year term.
| Property price | 10% deposit | Loan amount | Est. monthly repayment | Est. total repaid over 20 years |
|---|---|---|---|---|
| ₦10 million | ₦1 million | ₦9 million | ₦85,400 | ₦20.5 million |
| ₦20 million | ₦2 million | ₦18 million | ₦170,700 | ₦41.0 million |
| ₦30 million | ₦3 million | ₦27 million | ₦256,100 | ₦61.5 million |
| ₦50 million | ₦5 million | ₦45 million | ₦426,800 | ₦102.4 million |
| ₦75 million | ₦7.5 million | ₦67.5 million | ₦640,200 | ₦153.7 million |
| About ₦111 million | About ₦11.1 million | ₦100 million | ₦948,500 | ₦227.6 million |
These are our own estimates using a standard amortisation calculation. They exclude valuation fees, insurance, legal charges and any management fees your lender may add, so ask for a full breakdown before you sign.
Two things stand out. First, because the rate is fixed, the monthly figure will not creep up if interest rates move, which is the main protection for a borrower. Second, the ₦100 million ceiling means the largest property you can finance with a 10% deposit is roughly ₦111 million. Anything above that needs a bigger deposit from your own pocket.
What is MREIF, and who runs it?
MREIF was set up under the Tinubu administration’s housing drive and is sponsored by the Ministry of Finance Incorporated (MOFI), the federal government’s investment arm. ARM Investment Managers runs it as fund manager, STL Trustees acts as trustee, and First Nominees is the custodian. The fund is registered with the Securities and Exchange Commission, has a ₦1 trillion programme size and a 99-year life.
Its money comes from MOFI and institutional investors such as pension fund administrators. Banks sit in front of it. They take your application, check your finances and the property, and administer the loan, while MREIF supplies the long-term funding that makes a 20-year, single-digit mortgage possible.
Mortgage lending under the fund began in 2025, and the numbers have climbed steadily.
| Reporting date | Mortgages | Value | States covered |
|---|---|---|---|
| June 2026 | 1,859 families | ₦128 billion | 25 |
| August 2026 | 2,018 mortgages | ₦140 billion | 27 |
| November 2026 | 2,300+ Nigerians | ₦160 billion | 27 |
In June, the State House said the average beneficiary was 42 years old. By August, 21 financial institutions were lending under the scheme.
Who can apply?
The president described the loan as open to eligible Nigerians wherever they live. Based on the lender guidelines published so far, here is what you should expect to meet:
- Verifiable income: Salaried workers and business owners can both apply, but you must prove you earn enough to carry the repayments. The loan amount you get depends on affordability, not on the ₦100 million cap.
- A decent credit record: Lenders check your credit history before approving anything.
- Age: Guidelines published when the fund launched required borrowers to be at least 21 and no older than 60 when the loan ends. Check this with your bank, since individual lenders set their own rules.
- A completed house: The mortgage finances finished residential properties, not bare land or buildings still going up.
- Clean title documents: The property must have acceptable registered title papers, such as a Certificate of Occupancy.
- One property per mortgage: MREIF financing covers a single unit per buyer. You can buy more houses, but with your own money.
- Your 10% deposit: This can come from savings, and eligible pension contributors may be able to draw part of their RSA balance for it.
Couples can apply jointly, which lets both incomes count towards what you can borrow. That matters in practice. For a ₦40 million house, one salary may not stretch far enough, while two together might.
Nigerians abroad are not shut out either. FirstBank has said diaspora applicants can access its MREIF loan with credit reports from international agencies such as Equifax, plus a few extra documents.
How to apply for the ₦100m housing loan, step by step
You do not apply to the Presidency, and you do not pay anyone to “fast-track” your file. The process runs through MREIF’s official channels and the participating banks.
- Check the official information: Start at the MREIF homebuyers page (mreif.com.ng/homebuyers) to read the eligibility conditions and application instructions.
- Pick a participating lender: FirstBank, Stanbic IBTC and Sterling Bank all run MREIF home loans, among other institutions. Compare their fees, processing times and any differences in terms.
- Choose your property: Find a completed home with proper registered title. Do this before paying a seller anything, and ask the lender to confirm the property is acceptable.
- Submit your application: Fill in the bank’s online form or visit a branch, and attach your documents.
- Wait for assessment: The lender reviews your income and credit record, values the property and verifies the title.
- Review the offer carefully: Confirm the deposit, monthly repayment, fees and insurance in writing before you accept.
- Pay the deposit and complete the transaction: Once documentation is perfected, the loan is disbursed and the property is transferred.
Speaking at a recent FirstBank webinar on the scheme, an official said a smooth application can potentially be completed within a month. Treat that as a best case, not a promise. Title verification is usually where delays happen.
Documents you will probably need
Requirements vary by bank, but expect to be asked for most of the following.
| Document | Why it is needed |
|---|---|
| Completed application form | Starts the formal request |
| Valid means of identification | Confirms who you are |
| Recent payslips or business income evidence | Proves you can repay |
| Bank statements | Shows your income and spending pattern |
| Tax documents | Supports your income declaration |
| Offer or sale letter from the seller or developer | Shows the price and the deal |
| Copy of the property title documents | Lets the lender verify ownership |
MREIF vs FMBN: do not mix them up
Plenty of people will see “₦100 million” and “federal government” and assume it is all one scheme. It is not. Three different products are in circulation right now.
| MREIF Home Loan | FMBN NHF Mortgage | FMBN Diaspora Mortgage | |
|---|---|---|---|
| Maximum loan | ₦100 million | ₦50 million | ₦100 million |
| Interest rate | 9.75% fixed | 6% | 9% |
| Maximum tenor | 20 years | 30 years | 10 years |
| Minimum deposit | 10% | Set under NHF rules | Per FMBN terms |
| Who it is for | Eligible Nigerians through participating banks | Registered National Housing Fund contributors | Nigerians living abroad |
| How to apply | Through MREIF and participating banks | Through an accredited primary mortgage bank | Through the NiDCOM/FMBN portal |
The FMBN route has its own conditions. Contributors must meet the National Housing Fund requirements, including a period of contributions, and individuals apply through a licensed primary mortgage bank, not directly to FMBN. If you are a salaried worker already paying into the NHF, the 6% rate may be worth a close look before you default to the bigger MREIF loan.
What the scheme does not solve
Good news deserves a sober second look, and a few caveats are worth stating plainly.
Reach is still small: About 2,300 mortgages across 27 states is real progress, and it is also a tiny fraction of Nigerian households that need housing. MOFI’s national coordinator, Sani Yakubu, has said the country needs at least 700,000 new housing units a year and currently builds roughly 100,000.
Supply and price matter as much as finance: A cheap loan does not help much if there are few completed, titled houses at prices ordinary earners can afford. Land documentation, valuation and infrastructure all affect whether the scheme reaches people outside Lagos and Abuja, where most applications still come from.
The loan is capped by your income, not by the headline: Very few borrowers will qualify for the full ₦100 million. At that level, the monthly repayment is close to ₦950,000.
Total cost is large: At 9.75% over 20 years, a borrower repays more than double what they borrowed. The rate is low by Nigerian standards, but the total bill still deserves a hard look.
For people who cannot afford any mortgage, the government points to its social housing efforts. Tinubu said 100 free homes were handed to widows in Kaduna State and another 50 to wives of fallen military personnel in Ibadan, Oyo State. The Family Homes Fund also carries a mandate to deliver 500,000 homes.
Protect yourself from loan scams
Whenever a government scheme with big numbers hits the news, fraudsters follow within hours. Keep these rules in mind:
- Apply only through the official MREIF website or a participating bank’s own channels.
- Do not pay agents or “contacts” who promise guaranteed approval.
- Never pay a property seller before the lender confirms the house and its title are acceptable.
- Confirm every fee in writing and pay only into the bank’s official accounts.
Frequently asked questions
How much can I borrow under Tinubu’s housing loan?
Up to ₦100 million, but the amount you get depends on your income and what the lender judges you can afford.
What is the interest rate?
9.75% per annum, fixed for the whole loan period.
How long do I have to repay?
Up to 20 years.
How much deposit do I need?
At least 10% of the property’s value. On a ₦10 million house, that is ₦1 million.
Can I use my pension for the deposit?
Eligible pension contributors may use part of their Retirement Savings Account balance towards the equity contribution, subject to applicable rules. Ask your lender and your pension administrator.
Can I buy land or a house that is still being built?
Generally no. The mortgage finances completed residential properties with registered title documents.
Can my spouse and I apply together?
Yes. Joint applications are allowed, and both incomes can be counted.
Is the money a grant?
No. It is a repayable mortgage with interest.
Which banks offer the MREIF home loan?
FirstBank, Stanbic IBTC and Sterling Bank are among the participating lenders. The State House reported 21 financial institutions lending under the fund as of August 2026.