Getting access to business funding after leaving a Nigerian university or polytechnic can come with a long list of questions, especially when the amount involved runs into millions of naira. For graduates with a business idea, an existing enterprise or a technology driven project, the Central Bank of Nigeria created a financing framework that reaches beyond the usual small business support programmes. One of the figures attached to the scheme immediately attracts attention, with eligible individual applicants able to seek financing of up to ₦5 million under the graduate focused term loan component.
The Central Bank of Nigeria’s Tertiary Institutions Entrepreneurship Scheme, widely known as TIES, however, comes with specific rules that determine who can apply, the type of business that can qualify, the documents that must be presented and the way the financing is expected to be repaid. The ₦5 million figure therefore represents a maximum financing limit rather than an automatic payment to every graduate who submits an application. Understanding those details becomes important before preparing documents or building a business proposal around the scheme.
TIES was introduced as an entrepreneurship financing initiative for graduates of Nigerian universities and polytechnics, with its structure covering term loans, equity investment and developmental grants. The graduate term loan is the part most relevant to an individual seeking business financing, while the other components operate under different conditions and should not be confused with a personal cash grant.
The ₦5 Million Graduate Financing Window
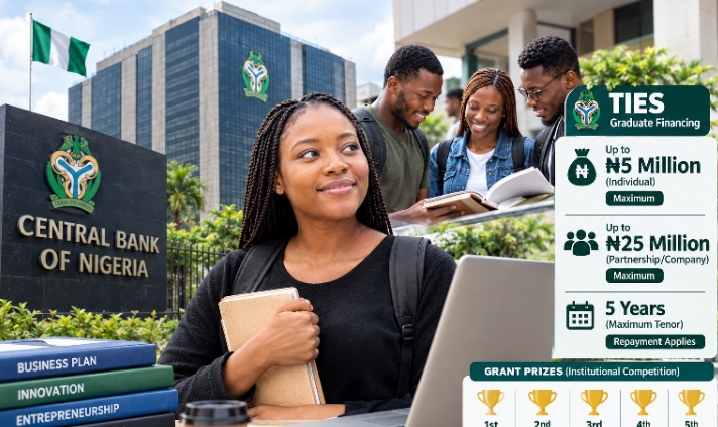
The graduate term loan component provides an opportunity for an eligible individual to seek financing of up to ₦5 million for a qualifying entrepreneurial project. The facility can cover an individual project, sole proprietorship or small company project within the applicable structure. A separate ceiling of up to ₦25 million applies to qualifying partnership or company projects involving up to 5 individual partners, making the structure different depending on how the proposed business is organised.
The financing is repayable, which places TIES firmly within the category of business financing rather than free government cash support. The maximum tenor is 5 years, while the guidelines provide for a maximum moratorium of 12 months on principal and interest, subject to the approved terms of the facility. Repayment is therefore part of the arrangement, and an applicant needs to approach the opportunity with a viable business model rather than treating the ₦5 million figure as personal income.
The actual amount approved can also differ from the amount requested. Project requirements, business projections, documentation, appraisal, repayment capacity and the assessment carried out by the participating financial institution can all affect the final financing decision. A graduate requesting ₦5 million therefore should understand that the scheme’s published maximum does not mean every successful applicant receives ₦5 million.
The Graduate Rules Applicants Need
Eligibility starts with the applicant’s educational background. The graduate term loan is designed for graduates of Nigerian universities and polytechnics, with the published requirements covering applicants who possess a BSc, HND or equivalent qualification. The requirement is tied to the graduate focused nature of the scheme, which means the programme is not simply an open business loan available to every Nigerian with a business idea.
Another important requirement concerns the National Youth Service Corps. The CBN’s published TIES information requires an NYSC discharge certificate or exemption certificate for the graduate loan component. The applicant must also be not more than 7 years post NYSC, making the timing of graduation and national service relevant when assessing eligibility.
The scheme also requires evidence of entrepreneurship training from a Nigerian university or polytechnic. This is an important part of the application because having a degree, NYSC certificate and business registration does not by itself cover every stated requirement. The entrepreneurship certificate is expected to show participation in entrepreneurship training through the relevant institution.
The Entrepreneurship Certificate Requirement
The entrepreneurship training certificate deserves particular attention because it can easily be overlooked during preparation. The CBN’s published information states that the certificate should come from an entrepreneurship or skill acquisition centre of a Nigerian university or polytechnic. The requirement connects the financing scheme directly to entrepreneurship education within tertiary institutions.
The CBN also makes a distinction concerning certificates issued by private Entrepreneurship Development Institutions. Such a certificate is not accepted as the required university or polytechnic entrepreneurship training certificate for this purpose. Applicants therefore need to examine the source of their certificate before assuming that any entrepreneurship training document will satisfy the requirement.
A graduate who has a BSc, has completed NYSC and has registered a business with CAC may still need to address this particular requirement. Preparing the documents early can help an applicant identify gaps before reaching the application stage, especially where the university or polytechnic certificate needs to be obtained from an entrepreneurship or skill acquisition centre.
The 7 Year Post NYSC Rule
The timing requirement is another area that can determine eligibility. The CBN states that the applicant must be not more than 7 years post NYSC. This means the scheme is aimed at relatively recent graduates rather than placing the graduate financing window on an unlimited timeline.
The NYSC discharge or exemption certificate consequently serves more than a documentation purpose. It also provides a reference point for assessing the applicant’s position within the scheme’s post service eligibility period. Applicants who completed national service several years ago should therefore check their dates carefully before investing time in preparing a full application.
The undergraduate category is also outside this particular graduate term loan window. A person currently studying for a degree or diploma cannot simply apply under TIES by presenting an idea for a future business. The financing structure is directed at eligible graduates who meet the stated requirements.
Businesses TIES Can Finance
The business activity is just as important as the applicant’s qualification. TIES was structured to support entrepreneurial activities across several sectors, with eligible areas extending beyond the traditional image of agriculture or small retail businesses. Agribusiness is included, covering activities such as production, processing, storage and logistics.
Technology driven businesses also fall within the scheme’s stated areas. The CBN identifies application and software development, business process outsourcing, robotics and data management among the areas that can qualify. This creates room for graduates building technology businesses or services that depend heavily on digital skills and innovation.
Creative businesses also form part of the eligible sectors. The published categories include entertainment, artwork, publishing, culinary and event management, fashion, photography and beauty or cosmetics. A graduate operating a creative enterprise can therefore potentially structure a TIES proposal around an eligible activity provided the project meets the broader financing requirements.
Science Technology Projects
The scheme also recognises science and technology based entrepreneurial activities. Examples identified by the CBN include medical innovation, robotics, ticketing systems, traffic systems, renewable energy and waste management. The range shows that TIES was designed to support businesses capable of producing practical products and services rather than being limited to one traditional sector.
The CBN can also introduce additional eligible activities from time to time. That means applicants should examine the current scheme requirements when preparing their proposals instead of relying solely on descriptions copied from older opportunity articles or social media posts.
The quality of the project remains important even where the business falls within an eligible sector. The guidelines give priority to innovative entrepreneurial activities with strong potential for export, job creation and transformational impact. An applicant therefore needs to demonstrate how the proposed business works, who it serves, how revenue will be generated and how the financing will be used.
Trading Activities Are Excluded
One of the clearest restrictions concerns ordinary trading. The CBN states that trading activities are not eligible under the scheme. This is an important distinction for graduates who may initially think of TIES as a general business loan for buying goods and reselling them.
A proposal built simply around purchasing clothes, shoes, phones or other goods for resale would therefore not fit the stated financing scope as ordinary trading. The business proposal needs to demonstrate an eligible entrepreneurial activity rather than presenting TIES as a source of capital for routine buying and selling.
Applicants should pay attention to the actual nature of their business rather than changing the description of a trading operation without changing the underlying activity. The proposal should accurately explain the business model, the production or service process, the customers, the expected revenue and the economic value created through the project.
Greenfield Projects
TIES recognises both new and existing businesses through the distinction between greenfield and brownfield projects. A greenfield project refers to a new business or project that is being established, while a brownfield project relates to an existing business.
The original guidelines provided a 40 percent to 60 percent focus between greenfield and brownfield projects. This distinction means a graduate does not necessarily need to have operated a business for several years before considering the scheme. A properly developed new business proposal can fall within the framework, provided the applicant and project satisfy the applicable requirements.
Existing businesses can also seek financing where the proposed use of funds fits the scheme. The business therefore needs to show a clear purpose for the requested facility, whether the financing is connected to establishing a new operation, expanding an existing enterprise or developing an eligible project.
The Documents Applicants Need
Document preparation forms a major part of the application process. The CBN identifies the BSc, HND or equivalent certificate, NYSC discharge or exemption certificate and the required university or polytechnic entrepreneurship training certificate among the core documents.
Financial information is also required because the facility is based on business financing rather than a general cash distribution. Applicants may need projected income statements, statements of affairs and cash flow projections. Start ups and businesses that are less than 3 years old are specifically expected to provide cash flow projections as part of the financial information.
The business plan is another major requirement. It should provide details of the proposed project, its financial position or projections and the economic benefits expected from the activity. A strong application therefore requires more than filling personal information into an online form. The applicant needs to explain the business clearly enough for the financing process to assess the project.
NIN, BVN, TIN Requirements
The broader TIES documentation also includes important identity and business information. Applicants should prepare their National Identification Number, Bank Verification Number and Tax Identification Number where applicable, alongside the other documents requested through the application process.
The NIN linked phone number is also part of the information associated with the scheme’s documentation requirements. Applicants should ensure that their personal details are consistent across their identification and banking records because discrepancies can create additional verification questions during financial processing.
Business registration documents are also relevant. The CBN’s original TIES information refers to CAC registration documentation and a corporate bank account within the required application information. This reinforces the fact that the facility is intended for identifiable business activity rather than an informal personal cash request.
CAC Registration
Business registration becomes particularly important when preparing the financing structure. The original TIES framework describes the applicant as applying as a business entity and requires evidence of registration through the relevant Corporate Affairs Commission documents.
An individual project can fall within the ₦5 million category through the applicable individual, sole proprietorship or small company structure. The higher ₦25 million ceiling is associated with a partnership or company project involving a maximum of 5 individual partners.
Applicants should therefore establish the appropriate business structure before completing the financing process. The registration details, business plan, bank information and financial projections should tell the same story about the enterprise.
The Application Process
The application begins with checking the eligibility requirements before opening the application process. A graduate should first confirm the educational qualification, NYSC status, post NYSC period and entrepreneurship training certificate. This initial check can prevent an applicant from spending time developing a proposal without meeting the basic graduate requirements.
The next stage involves putting the business documentation together. The applicant should have the relevant CAC documentation, identification details, banking information, entrepreneurship certificate and educational records available. The business plan and financial projections should also be prepared before the application is submitted.
The applicant then proceeds through the approved TIES application route and supplies the information requested through the portal. Documents required by the scheme are uploaded electronically as part of the process. The CBN’s published FAQ states that original degree and NYSC documents do not need to be physically handed over merely because they are being used as supporting documents, since they are scanned and uploaded through the portal.
Business Plan Preparation
The business plan deserves serious attention because the loan is connected to the viability of the proposed project. The document should explain the business, the problem it addresses, the product or service being offered, the target customers and the way the business will generate revenue.
Financial projections should also match the business story. If a graduate requests ₦5 million, the proposal should clearly explain how the money will be allocated and how the resulting business activity is expected to generate enough revenue to support repayment. Inflated figures without a clear commercial explanation can weaken the overall proposal.
The economic benefits of the project should also be presented clearly. Job creation, innovation, export potential and broader economic impact are areas recognised within the TIES framework. The applicant should therefore connect the requested financing to measurable business activities rather than simply stating that the money will be used to grow the business.
Loan Assessment
Submission of an application does not automatically result in approval. The participating financial institution is responsible for due diligence and credit assessment, which means the proposal and supporting documentation go through an appraisal process.
The Bank of Industry was identified by the CBN as the participating financial institution responsible for processing and disbursing the loan during the pilot phase. The wider TIES guidelines also provide for participating financial institutions to undertake relevant assessment and due diligence.
Applicants should therefore expect a financing process rather than an instant approval process. The institution needs to assess the project, documentation, financial information and other applicable conditions before a final financing decision can be made.
The Loan Interest Rate
Interest rate information needs to be handled carefully because the CBN’s published TIES material contains a rate transition. The official FAQ states that the facility was priced at 5 percent per annum, with the rate becoming 9 percent effective from March 1, 2022, or as may be prescribed by the CBN.
That wording is important when discussing the facility in 2026. Applicants should not simply describe TIES as a permanent 5 percent loan without mentioning the subsequent rate provision contained in the official CBN material.
The final terms applicable to an approved facility should be confirmed through the authorised financing process. Monetary conditions have changed since TIES was launched, so applicants should rely on the current terms presented through the official process rather than an old social media post or an outdated opportunity listing.
Repayment Structure
TIES is structured as repayable financing. The CBN states that principal and interest can be repaid monthly or quarterly depending on the cash flow cycle of the business and the approved repayment arrangement.
The maximum tenor is 5 years. The guidelines also provide for a maximum moratorium of 12 months on principal and interest, subject to the conditions approved for the facility.
A moratorium should not be interpreted as free money or permanent exemption from repayment. It provides a period during which the approved repayment obligations can be deferred under the agreed facility terms, after which the repayment schedule takes effect.
Collateral Requirements
TIES has a distinctive approach to collateral. The CBN identifies the applicant’s first degree certificate, NYSC discharge or exemption certificate and a duly signed Global Standing Instruction among the relevant security arrangements.
The scheme also identifies a third party guarantee from an eligible professional or public servant. Examples provided by the CBN include a senior civil or public servant, reputable clergy member, lawyer, accountant, banker or medical doctor.
Applicants should understand these requirements before submitting an application because the guarantee requirement involves another person and should therefore be arranged carefully. The supporting person’s eligibility should be considered alongside the other documentation requirements.
How The ₦5 Million Is Disbursed
TIES should not be approached as a personal cash giveaway. The original guidelines provide for disbursement in tranches and subject to approved terms and project milestones.
That structure is consistent with the purpose of the facility, which is to finance identifiable business activity. The financing is therefore connected to the approved project and its implementation rather than being unrestricted personal spending money.
Applicants should also avoid assuming that every approved facility will be transferred as one unrestricted lump sum. The actual disbursement arrangement depends on the approved financing structure, project requirements and conditions imposed by the participating financial institution.
The ₦25 Million Option
The larger financing ceiling applies to a different structure. A qualifying partnership or company project involving up to 5 individual partners can potentially seek financing of up to ₦25 million.
This does not mean that 5 graduates can simply combine their names and automatically receive ₦25 million. The project, company or partnership still has to satisfy the relevant requirements and undergo the applicable appraisal process.
The higher ceiling is therefore better understood as a project financing limit attached to a qualifying business structure. Applicants considering this route need to organise their partnership, company documentation, business plan and financial projections accordingly.
TIES Equity Investment
The term loan is only 1 part of the broader TIES framework. The equity investment component operates differently and is designed to provide capital for start ups, expansion of established businesses and revival of ailing entrepreneurial businesses.
The CBN’s guidelines connect this component to the AGSMEIS Equity Window. The investment period can extend up to 10 years under the scheme’s conditions, with the original guidelines providing for a 3 year lock in period.
Equity investment should not be confused with the ₦5 million graduate term loan. The financial structure, purpose and conditions are different, and the equity component does not mean every graduate applicant is entitled to receive a separate cash award.
The Developmental Grant
The grant component is another area that has generated confusion around TIES. The developmental grant is not a general grant that individual graduates can apply for and collect as personal business cash.
The CBN structured this component around Nigerian universities and polytechnics competing in a national biennial entrepreneurship competition. The grants are directed toward top performing institutions for development of winning innovations and related research and development activities.
The original TIES summary listed ₦150 million for 1st place, ₦120 million for 2nd place, ₦100 million for 3rd place, ₦80 million for 4th place and ₦50 million for 5th place. Those figures relate to the institutional competition and should not be presented as personal graduate grants.
Application Fees
The CBN states that no payment is required for submission or processing of a TIES application. This is one of the details applicants should remember before dealing with anyone claiming to be an official agent.
The CBN also states that it does not have agents for TIES and directs applicants to submit personally through the approved application channel. A person asking for money to secure a TIES slot, speed up an application or guarantee approval is therefore not following the published CBN position.
Applicants should keep their documents under their control and use the official application route rather than sending sensitive information to individuals through WhatsApp, social media or unofficial forms.
The Official Application Portal
The official TIES application portal identified by the CBN is cbnties.com.ng. Applicants should access the scheme through the official channel and verify that they are using the correct website before entering personal, educational, banking or business information.
The CBN’s official TIES information is available through the Central Bank of Nigeria website, while the published guidelines provide additional details on the structure and operation of the scheme.
Applicants should treat links forwarded by individuals with caution. The safest approach is to reach the official CBN TIES information through the Central Bank’s own website and follow the application route provided there.
TIES Timeline
The TIES scheme was introduced as a long running entrepreneurship financing framework rather than a short campaign with a single annual application date. The official CBN FAQ states that the scheme is to operate for 10 years, not exceeding December 31, 2031, depending on project complexity.
That date should not be mistaken for an individual application deadline. It describes the broader duration of the scheme and does not mean every applicant can wait until December 31, 2031 or that every financing window will remain unchanged throughout the period.
There is also no official CBN information establishing September 30, 2026 as a general deadline for the graduate TIES term loan. Applicants should therefore avoid treating September 30, 2026 as a confirmed TIES closing date unless a fresh official announcement establishes one.
The Main Points To Remember
The TIES graduate term loan is built around a specific group of applicants. A person seeking the facility should have a BSc, HND or equivalent qualification, an NYSC discharge or exemption certificate, the required university or polytechnic entrepreneurship training certificate and should be not more than 7 years post NYSC.
The business must also fit the scheme’s eligible areas. Agribusiness, information technology, creative industries and science and technology activities are among the recognised sectors, while ordinary trading activities are excluded. The proposal needs to explain the business clearly and show how the financing will be used.
The maximum individual financing amount is ₦5 million, while a qualifying partnership or company project involving up to 5 individual partners can potentially access up to ₦25 million. Both figures represent maximum financing limits rather than guaranteed payments.
Final Application Checklist
Before submitting a TIES application, a graduate should have the required educational certificate, NYSC discharge or exemption certificate and university or polytechnic entrepreneurship training certificate ready. NIN, BVN, TIN, NIN linked phone information and the relevant CAC documents should also be prepared where required.
The business plan should explain the project, financial projections, expected economic benefits and the proposed use of funds. Start ups and businesses under 3 years should pay particular attention to the required cash flow projections, while existing businesses should ensure their statements and supporting records accurately reflect their operations.
The applicant should also understand the repayment obligation, possible moratorium, collateral arrangements, third party guarantee requirement and financing assessment before applying. TIES can provide access to substantial business financing, but the process is built around a real enterprise, supporting documentation and repayment rather than an automatic transfer of ₦5 million.
For graduates considering TIES in 2026, the central point is straightforward. The scheme provides a route to seek substantial financing for qualifying entrepreneurial projects, with the graduate term loan offering up to ₦5 million for an eligible individual project and up to ₦25 million for qualifying partnership or company projects. The opportunity becomes relevant when the applicant, business, documents and financing plan all fit the published requirements.